
Navigating the labyrinthine world of healthcare insurance in Singapore can feel like deciphering an ancient scroll. Acronyms abound, policies overlap, and the line between “private” and “public” often blurs. One question that frequently arises, particularly amongst the gainfully employed, is: “Is work-provided healthcare considered private insurance?” The answer, as is often the case with matters of health and finance, is multifaceted and requires a nuanced understanding of the underlying principles.
Let’s embark on a journey to demystify this concept, shedding light on the intricacies of employer-sponsored healthcare plans and their relation to the broader private insurance landscape.
Decoding the DNA of Work-Provided Healthcare
Work-provided healthcare, at its core, is a form of insurance coverage offered by an employer as part of an employee’s compensation package. This coverage typically encompasses a range of medical benefits, from outpatient consultations and specialist referrals to hospitalization and even dental care. The specifics, however, can vary wildly depending on the employer, the size of the company, and the negotiated terms with the insurance provider.
Consider this: a multinational corporation might offer a comprehensive suite of benefits, including coverage for overseas medical treatment and wellness programs, while a smaller startup might provide a more basic plan focused on essential medical needs.
Private Insurance: A Spectrum of Options
Private health insurance, in contrast, is a broader category encompassing any health insurance plan purchased independently, outside the realm of government-subsidized programs or employer-sponsored schemes. Individuals opt for private insurance for various reasons: to supplement their existing coverage, to gain access to a wider network of healthcare providers, or to secure more comprehensive benefits than what their employer offers.
Private insurance policies often come with a higher degree of customization, allowing individuals to tailor their coverage to their specific health needs and risk profiles. Think of it as bespoke tailoring versus off-the-rack clothing. Both serve the purpose, but one offers a more personalized fit.
Is Work-Provided Healthcare a Species of Private Insurance? A Qualified “Yes”
The crux of the matter lies in understanding that work-provided healthcare typically is a type of private insurance, albeit one with a unique set of characteristics. The employer essentially acts as a conduit, negotiating with private insurance companies on behalf of their employees to secure group rates and coverage. This collective bargaining power often results in more favorable premiums and broader coverage than an individual might obtain on their own.
However, it’s crucial to recognize the limitations. Work-provided healthcare is intrinsically linked to employment. If an individual leaves the company, their coverage generally ceases. This is where the need for supplemental private insurance or a portable insurance plan becomes apparent, providing continuous coverage regardless of employment status.
The Interplay with National Healthcare Frameworks: A Singaporean Perspective
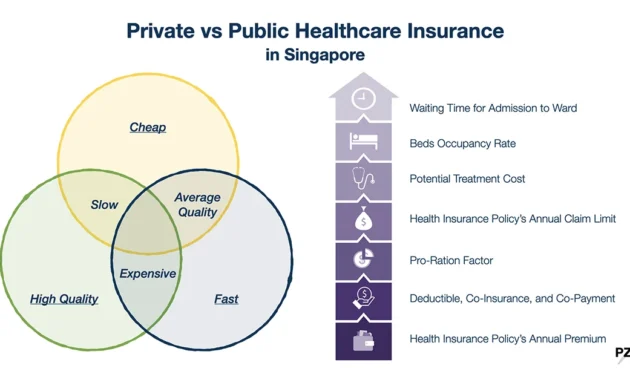
In Singapore, the healthcare landscape is a carefully calibrated blend of public and private sectors. The government’s Medisave, Medishield Life, and Medifund schemes form the bedrock of universal healthcare coverage, providing a safety net for all citizens and permanent residents. Work-provided healthcare and individual private insurance plans then augment this base, offering enhanced benefits and greater choice.
Many Singaporeans opt for Integrated Shield Plans (IPs), which are private insurance policies that work in conjunction with Medishield Life to provide higher claim limits, access to private hospitals, and potentially shorter waiting times. Work-provided healthcare often includes or contributes towards the cost of these IPs, further blurring the lines between employer-sponsored coverage and individual insurance choices.
Nuances and Caveats: A Word of Caution
While work-provided healthcare is generally a boon, it’s essential to scrutinize the policy details meticulously. Pay close attention to: the coverage limits, the network of participating healthcare providers, any pre-existing condition exclusions, and the process for making claims. Don’t hesitate to compare the benefits offered by your employer’s plan with those available through individual private insurance policies to determine if supplemental coverage is warranted.
Furthermore, be aware of the portability of your health insurance. Some employers offer the option to convert their group policy to an individual policy upon leaving the company, albeit often at a higher premium. Understanding these options is crucial for ensuring continuity of coverage during periods of career transition.
Empowerment Through Knowledge: Making Informed Decisions
Ultimately, the question of whether work-provided healthcare constitutes “private insurance” is less important than understanding the scope and limitations of your coverage. By familiarizing yourself with the nuances of your employer’s plan, comparing it to other available options, and considering your individual health needs, you can make informed decisions that safeguard your well-being and financial security. Healthcare insurance, after all, is not merely a policy; it’s an investment in your most precious asset: your health.
By understanding the intricate relationship between work-provided healthcare and the broader private insurance market, you can navigate the complexities of the Singaporean healthcare system with greater confidence and clarity, ensuring that you and your loved ones receive the care you deserve.