
Navigating the labyrinthine world of healthcare can feel like charting a course through a dense fog. For those eligible for Medicare, the choice between Original Medicare and Medicare Advantage often looms large, a pivotal decision that can significantly impact access to care, out-of-pocket expenses, and overall peace of mind. This isn’t merely selecting a health plan; it’s choosing the framework that will support one’s well-being for years to come. Imagine it like selecting the architectural blueprint for your golden years—will you opt for the classic, sturdy foundation of Original Medicare, or the modern, all-inclusive design of Medicare Advantage?
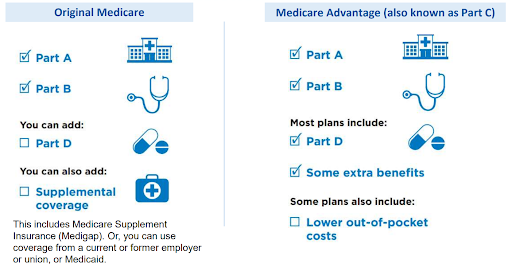
Original Medicare, often dubbed traditional Medicare, consists of two primary parts: Part A (hospital insurance) and Part B (medical insurance). Think of Part A as your safety net for inpatient care, covering hospital stays, skilled nursing facility care, hospice, and some home healthcare. Part B, on the other hand, acts as a comprehensive outpatient shield, encompassing doctor visits, preventive services, durable medical equipment, and mental health services. This duo functions as a foundational healthcare framework, allowing beneficiaries the freedom to seek care from any provider nationwide who accepts Medicare assignment – a vast and reassuring network.
The allure of Original Medicare lies in its unparalleled flexibility. With Original Medicare, beneficiaries are not confined to a specific network of providers. This unfettered access means you can consult specialists across state lines, seek second opinions without referral constraints, and maintain established relationships with preferred physicians, regardless of their affiliation. This autonomy is a significant draw for individuals who value choice and control over their healthcare journey. However, this freedom comes at a price. Original Medicare typically requires beneficiaries to pay deductibles, coinsurance, and potentially a monthly premium for Part B. Moreover, it does not inherently include prescription drug coverage (Part D), dental, vision, or hearing benefits, necessitating the purchase of separate supplemental insurance, such as a Medigap policy, to fill these lacunae.
Medicare Advantage, also known as Medicare Part C, presents a different paradigm. These plans are offered by private insurance companies approved by Medicare, and they are mandated to cover everything that Original Medicare covers, often with added perks. Envision Medicare Advantage as a bundled package, frequently encompassing prescription drug coverage (Part D), and potentially extra benefits like dental, vision, hearing, and even fitness programs. This “one-stop-shop” approach simplifies healthcare management, streamlining coverage into a single plan and often capping out-of-pocket expenses through an annual maximum.
The attractiveness of Medicare Advantage stems from its potential for lower out-of-pocket costs and comprehensive benefits. Many Medicare Advantage plans offer lower monthly premiums than Original Medicare coupled with a Medigap policy. This can be particularly appealing to beneficiaries on fixed incomes. However, this cost-effectiveness often comes with trade-offs. Medicare Advantage plans typically operate within a network of providers, limiting choices and potentially requiring referrals to see specialists. The utilization of healthcare services may be subject to prior authorizations, adding a layer of administrative oversight. The breadth and depth of these networks, as well as the frequency of prior authorization requirements, can vary considerably across plans, necessitating careful scrutiny during the selection process. The lower premiums might be offset by higher cost-sharing when accessing services, depending on the specific plan design.
Consider the impact of network restrictions. With Original Medicare, a beneficiary could seamlessly see a world-renowned specialist across the country. In contrast, a Medicare Advantage plan might restrict access to specialists within a specific geographic area or require a referral from a primary care physician, potentially delaying or complicating access to specialized care. This consideration is crucial for individuals with chronic conditions or those who anticipate needing specialized medical attention.
The issue of prescription drug coverage is another critical differentiating factor. While Original Medicare necessitates a separate Part D plan for prescription drug coverage, many Medicare Advantage plans include this benefit. However, the formulary (list of covered drugs) and cost-sharing structure can vary significantly across plans. It’s crucial to meticulously compare formularies and cost-sharing arrangements to ensure that the plan adequately covers necessary medications at an affordable price. Unexpectedly high drug costs can quickly erode the perceived cost savings of a Medicare Advantage plan.
Deciding between Original Medicare and Medicare Advantage requires a holistic assessment of individual healthcare needs, financial circumstances, and personal preferences. Do you prioritize freedom of choice and access to any provider nationwide, even if it means paying higher premiums and potentially needing a supplemental insurance policy? Or do you prefer the convenience of a bundled plan with potentially lower monthly premiums and extra benefits, even if it means navigating network restrictions and potentially requiring prior authorizations? There’s no universal “better” choice; the optimal path depends on individual circumstances and priorities.
Think of it this way: Original Medicare is akin to a bespoke suit, tailored to your individual needs but requiring separate investments for each component. Medicare Advantage, on the other hand, is like an off-the-rack suit, offering convenience and potential cost savings but potentially lacking the perfect fit and customization. The key lies in understanding the nuances of each option and selecting the one that best aligns with your individual profile.
Ultimately, the decision between Original Medicare and Medicare Advantage is a deeply personal one. It requires careful consideration of healthcare needs, financial resources, and comfort level with network restrictions and administrative processes. By thoroughly evaluating these factors and seeking guidance from trusted sources, individuals can confidently navigate the complexities of Medicare and select the coverage option that best supports their long-term health and well-being.