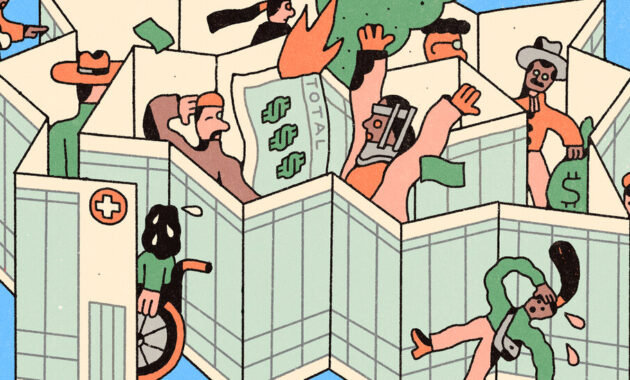

Do insurance companies, those behemoths of bureaucratic precision, truly hold the reins when it comes to taming the ever-escalating costs of healthcare? It’s a question that dances on the precipice of conspiracy theory and economic reality. One might envision them as valiant knights, wielding the sword of negotiated rates and the shield of utilization management against the dragon of runaway expenses. However, the reality, as is often the case in the labyrinthine world of healthcare finance, is far more nuanced and complex. Let’s unravel this intricate relationship, exploring the myriad ways insurance companies interact with healthcare costs, and ultimately, whether they are truly the guardians of our wallets.
The Negotiating Power: A Double-Edged Sword
Insurance companies, by virtue of their large subscriber base, wield significant bargaining power when negotiating rates with healthcare providers. Imagine them as powerful consortiums, representing a vast sea of patients. They can demand, and often receive, discounted rates for services. This is where the concept of “in-network” providers comes into play. Providers who agree to accept the insurance company’s negotiated rates gain access to a large pool of patients, creating a powerful incentive for participation.
However, this negotiating power isn’t a panacea. Firstly, in some geographic areas, particularly those with limited provider options, the insurance companies’ leverage is diminished. Providers, knowing they are the only game in town, can dictate terms, leaving the insurer with little room to negotiate downwards. Secondly, the complexity of healthcare billing, with its intricate coding systems and arcane terminology, often allows providers to obfuscate costs, making it difficult for insurers to truly assess the value of the services they are paying for. Consider the opacity inherent in bundled payments versus fee-for-service models; each presents its own challenges for cost containment.
Utilization Management: Gatekeepers or Obstructionists?
Another tool in the insurance company’s arsenal is utilization management, a suite of strategies designed to ensure that patients receive appropriate and necessary care. This often involves pre-authorization requirements for certain procedures or medications, as well as concurrent review of ongoing treatments. The intent is to prevent wasteful spending on unnecessary or inappropriate interventions.
Yet, utilization management is a lightning rod for criticism. Patients and providers often view it as an intrusive interference in the doctor-patient relationship, leading to delays in care and frustrating bureaucratic hurdles. The perception is that insurance companies are prioritizing cost containment over patient well-being, creating a climate of distrust and resentment. Imagine the chagrin of a physician whose carefully considered treatment plan is rejected by an insurance company algorithm, seemingly devoid of clinical context. The delicate balance between cost control and patient access is constantly tested.
The Administrative Burden: A Cost Driver in Disguise
While insurance companies strive to control costs directly through negotiation and utilization management, the administrative complexities they introduce can paradoxically contribute to rising healthcare expenses. The sheer volume of paperwork, coding requirements, and billing disputes generates a significant overhead for both providers and insurers. This administrative burden can divert resources away from direct patient care, adding to the overall cost of the system.
Consider the cost of maintaining a team of coding specialists to navigate the intricacies of ICD-10 and CPT codes. Or the expense of resolving billing discrepancies between providers and insurers. These seemingly mundane administrative tasks collectively represent a substantial drain on healthcare resources. Moreover, the time physicians spend on administrative tasks, rather than patient care, adds an indirect cost to the system.
The Role of Market Forces and Regulation: External Influences
Insurance companies operate within a broader economic and regulatory landscape that significantly influences healthcare costs. Market forces, such as the consolidation of hospital systems and the increasing demand for specialized services, can drive up prices, limiting the insurance companies’ ability to control costs. Government regulations, such as those related to drug pricing and coverage mandates, also play a crucial role in shaping the cost environment.
Imagine a scenario where a hospital system acquires a dominant market share in a particular region. This consolidation can reduce competition, allowing the hospital to command higher prices from insurers. Similarly, government regulations that mandate coverage for certain treatments or medications can increase the overall cost of insurance plans, even if those interventions are deemed medically necessary.
The Patient’s Perspective: Cost Sharing and Transparency
The rise of high-deductible health plans and other cost-sharing arrangements has shifted a greater portion of healthcare costs onto patients. While this may incentivize patients to become more price-conscious consumers, it can also lead to delayed or foregone care, particularly among those with limited financial resources. Furthermore, the lack of price transparency in healthcare makes it difficult for patients to make informed decisions about their care.
Imagine a patient facing a large deductible before their insurance coverage kicks in. They may be hesitant to seek medical care for a potentially serious condition, fearing the financial burden. Or consider the challenge of comparing prices for medical procedures when different providers charge vastly different amounts for the same service, with little explanation for the disparity. Greater price transparency and patient empowerment are crucial for driving value in healthcare.
Conclusion: A Complex Ecosystem of Influences
In conclusion, while insurance companies play a significant role in negotiating rates and managing utilization, they are not the sole determinants of healthcare costs. They exist within a complex ecosystem of market forces, regulatory mandates, administrative burdens, and patient behaviors. Attributing complete control to insurance companies is a gross oversimplification of a multifaceted problem. Ultimately, addressing the rising cost of healthcare requires a multi-pronged approach that tackles inefficiencies, promotes transparency, and incentivizes value-based care across the entire healthcare spectrum. Only through a collaborative effort involving providers, insurers, policymakers, and patients can we hope to bend the cost curve and ensure that healthcare remains accessible and affordable for all.